Global Debt Surpasses $365 Trillion as Soaring Borrowing Costs Fuel Unrest Across Europe

October 22, 2026

Worldwide debt held by governments, businesses and households increased by approximately $10 trillion during the first half of 2026, reaching a level equivalent to roughly $44,000 for every person on the planet.
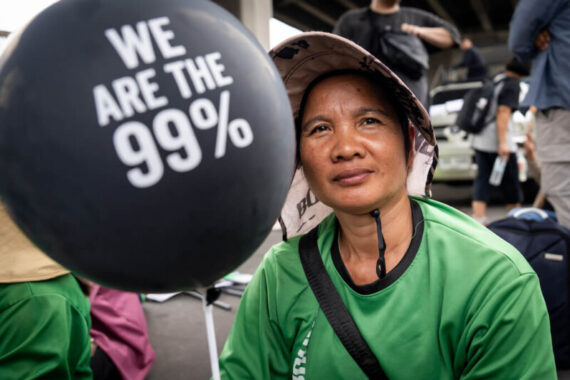
A protestor from the Assembly of the Poor demonstrates against the International Monetary Fund (IMF) and World Bank Group annual meetings outside the Queen Sirikit National Convention Center (QSNCC) in Bangkok, Thailand, on October 15, 2026. Photo by Anadolu Images.

G

lobal debt has surged beyond $365 trillion, placing governments under mounting financial pressure as rising interest payments consume public budgets and intensify economic frustration across Europe, where hundreds of thousands of protesters have taken to the streets demanding relief from soaring living costs.

According to the Institute of International Finance (IIF), worldwide debt held by governments, businesses and households increased by approximately $10 trillion during the first half of 2026, reaching a level equivalent to roughly $44,000 for every person on the planet.

The unprecedented debt burden comes as major economies face increasingly expensive borrowing conditions, forcing governments to allocate greater portions of their budgets to interest payments rather than public services.

The consequences have become particularly visible in France, where nationwide demonstrations over living costs, stagnant wages, unaffordable housing and underfunded education have highlighted growing dissatisfaction with the country’s economic direction.

More than 550,000 people participated in demonstrations across France on Saturday, according to the Interior Ministry, following weeks of student-led protests.

Similar demonstrations have erupted in Belgium, Italy and Portugal. While many gatherings remained peaceful, some descended into clashes, looting and fires.

France faces mounting debt crisis as borrowing costs surge

France has emerged as a major source of concern in European financial markets, with its government borrowing costs reaching their highest level since 2002.

The country currently pays approximately 5% to borrow money through 10-year government bonds, considerably higher than Germany’s 3.41%.

More strikingly, French borrowing costs have surpassed those of Italy and Greece, two countries that experienced severe financial difficulties during the eurozone sovereign debt crisis.

Only the United Kingdom, which operates outside the eurozone, currently faces higher borrowing costs among the major European economies examined.

The widening gap between French and German bond yields reflects investors demanding greater compensation for lending to Paris amid concerns about its fiscal outlook.

France’s public debt has reached approximately $4.2 trillion, equivalent to 118.5% of its gross domestic product, placing it fifth globally in absolute government debt.

The International Monetary Fund projects that France’s debt could climb to 121.8% of GDP by 2030, further complicating efforts to stabilize public finances.

Rising bond yields carry significant consequences for government spending.

When countries issue debt at higher interest rates, they must devote more resources to servicing their financial obligations, potentially leaving less funding available for hospitals, education, infrastructure and pensions.

Governments facing such pressures may eventually be forced to increase taxation, reduce public expenditure or borrow even more money.

The situation has revived memories of Europe’s sovereign debt crisis between 2010 and 2012, when soaring borrowing costs pushed countries including Ireland and Portugal into international financial assistance programs.

Global interest payments exceed annual defense spending

The debt challenge extends far beyond Europe.

The United States remains the world’s largest government debtor, with outstanding public debt reaching approximately $41.4 trillion, equivalent to 127% of its economy.

China follows with $22.5 trillion, or 104% of GDP, while Japan holds $8.7 trillion in government debt and has the highest debt-to-GDP ratio among major economies, at approximately 199%.

The United Kingdom’s government debt stands at $4.4 trillion, representing 102% of GDP, while Italy owes approximately $3.7 trillion, equivalent to 138% of its economy.

Germany, by comparison, carries $3.5 trillion in public debt, representing a significantly lower 65% of GDP.

The mounting financial obligations are accompanied by an increasingly expensive global interest bill.

Advanced economies paid more than $3.3 trillion in interest on government bonds over the past year, exceeding estimated annual worldwide spending on defense, artificial intelligence and clean energy individually.

Global defense expenditure stood at approximately $3.1 trillion, compared with $2.6 trillion for artificial intelligence and $2.3 trillion for clean energy.

The growing cost of servicing debt is also likely to affect households, as higher government borrowing costs can contribute to increased interest rates on mortgages, vehicle financing and consumer credit.

For policymakers, the challenge is balancing fiscal sustainability against growing public demands for economic relief.

With governments facing pressure to reduce deficits while citizens demand greater investment in essential services, the global debt surge is becoming not only a financial concern but an increasingly significant political challenge.

(Source: Aljazeera English)

Politics Today is dedicated to publishing insightful analyses in order to understand the changing nature of contemporary politics. It aims to contribute to the sound and constructive discussion of international affairs.